DemystifyYourCreditProfile
Understand how credit bureaus evaluate your repayment record, what lenders examine during credit appraisal, and how to maintain healthy financial habits over time.
Transparency First: No Guaranteed Score Hikes or Magical Fixes
First Truth Finance Consultations provides educational guidance and profile review services. We do not promise artificial credit score repair, removal of legitimate adverse remarks, or guaranteed loan sanctions. Credit scores are determined solely by authorized credit bureaus (such as TransUnion CIBIL, Experian, CRIF, and Equifax) based on actual financial history reported by regulated financial institutions.
Understanding Credit Score Ranges
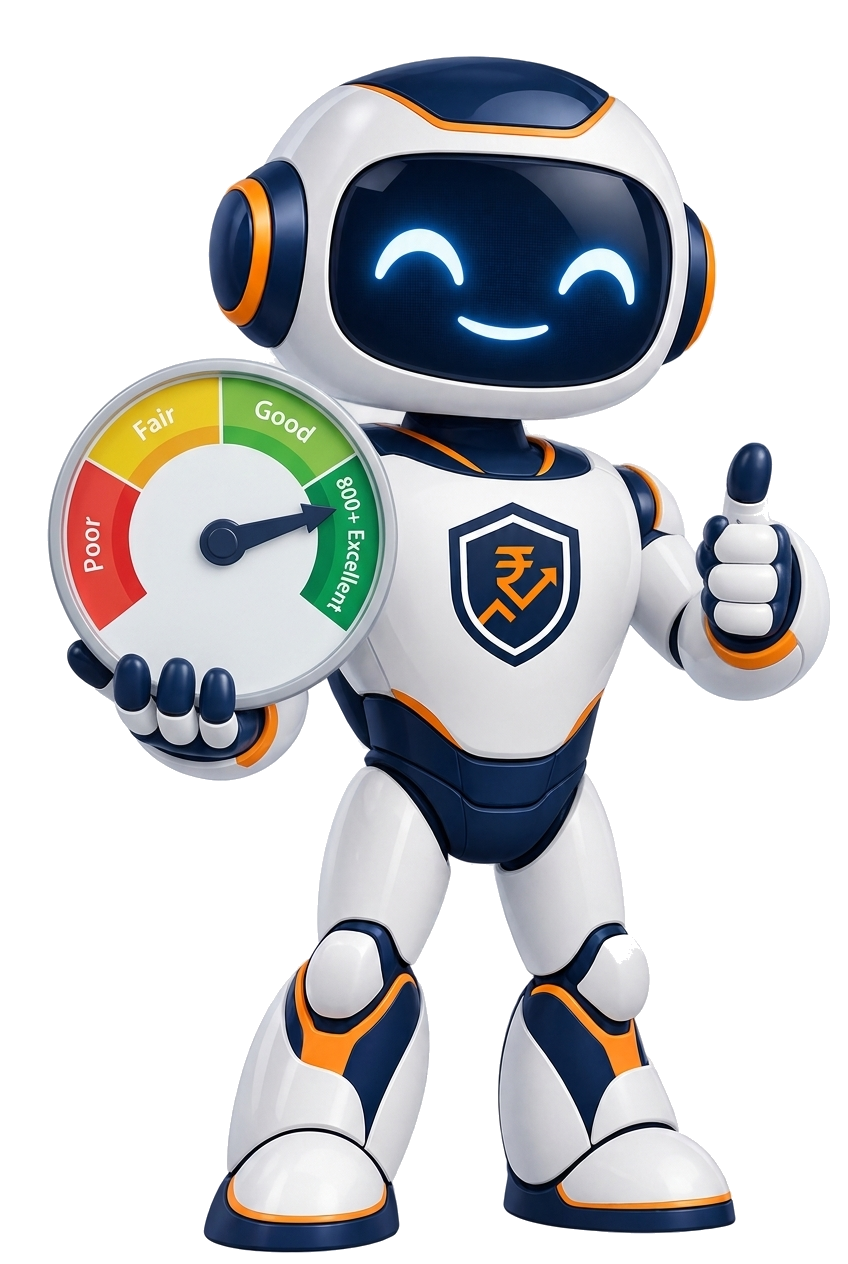
In India, consumer credit scores typically range from 300 to 900. Here is how institutional lenders generally perceive different score tiers:
Prime Borrower
Enjoys access to prime interest rates, quicker sanction turnaround, and higher negotiation leverage across major scheduled commercial banks and NBFCs.
Standard Eligible
Considered reliable by most institutional lenders. Standard interest rates and standard documentation guidelines apply for both secured and unsecured facilities.
Conditional Eligibility
May face stricter scrutiny, requirements for higher collateral security, co-applicants with stronger profiles, or slightly elevated risk-adjusted interest margins.
Needs Remediation
Fresh unsecured credit is generally restricted. Borrowers should prioritize clearing settled/written-off obligations and establishing clean repayment records over 12-24 months.
5 Ways We Assist Borrowers With Credit Guidance
Our principal consultant Shubham Jain and team provide step-by-step guidance to help you navigate credit bureau reports realistically.
Report Interpretation & Reading
Credit reports from bureaus (CIBIL, Experian, Equifax, CRIF High Mark) contain complex account status codes (DPD, settlement remarks, write-offs). We help you decipher what each section means.
Identifying Discrepancies & Dispute Process
Clerical mistakes, incorrect account statuses, or identity mix-ups sometimes occur. We guide you on the formal bureau dispute and rectification processes to correct legitimate errors.
Credit Utilization & Repayment Discipline
We analyze your existing credit card balances and active loan repayment structures, offering practical tips on structuring payments to lower credit utilization without unnecessary financial strain.
Cultivating Responsible Borrowing Habits
Building a durable credit score requires structured financial habits over time: setting auto-debits, avoiding frequent credit applications, and keeping older seasoned cards active.
Understanding the Underwriter's Lens
Beyond the raw 3-digit score, financial institutions evaluate Fixed Obligation to Income Ratio (FOIR), banking health, and employment stability. We explain how lenders evaluate your complete credit profile.
Core Factors That Shape Your Credit Score
Bureau scoring algorithms evaluate your financial behavior across five weighted dimensions.
Repayment Track Record (35%)
Highest ImpactTimely repayment of past loan EMIs and credit card balances is the single largest factor influencing your credit score. Even occasional missed payments can leave negative remarks.
Credit Utilization Ratio (30%)
High ImpactThe proportion of available revolving credit you utilize each month. Keeping credit card utilization below 30% of your sanction limit generally signals prudent credit management.
Credit History Age (15%)
Medium ImpactThe vintage of your oldest active credit account and average tenure of all borrowing accounts. A longer demonstrated history of responsible borrowing is positively viewed by lenders.
Credit Mix & Profile (10%)
Low ImpactA balanced combination of secured debt (home or vehicle loans) and unsecured debt (personal loans or credit cards) indicates capability in handling multiple debt obligations.
Hard Inquiries & New Applications (10%)
Low ImpactApplying for multiple loans or credit cards with several lenders within a compressed timeframe triggers multiple hard inquiries, which can temporarily dampen your credit score.
Have Questions About Your Credit Health?
Schedule a 1-on-1 consultation at our office in Rohtak or connect telephonically. We review your bureau report, explain what lenders will ask, and guide you towards financial readiness.